
Extreme Fear Has a Price Tag, and Right Now It's a Discount
What separates those treating this correction as opportunity from those who keep getting run over by it.

Bitcoin closed June down roughly 20 percent, its worst month in four years, and opened July trading in the high $50,000s, a level last seen 21 months ago. From October's peak near $126,000, that is a decline of more than half. By any conventional measure, this looks like capitulation. The Fear and Greed Index has spent most of July sitting in the mid 20s, a reading multiple providers classify as Fear bordering on Extreme Fear. The crowd, by every available metric, is scared.
And yet two very different groups are looking at the same chart and reaching opposite conclusions.
U.S. spot Bitcoin ETFs recorded about $4.06 billion in net outflows in June, the deepest monthly redemption since the products launched, led largely by outflows from the largest fund in the category. That is real institutional money walking out the front door. At the same time, on chain data tracked by CryptoQuant shows wallets holding meaningful Bitcoin balances added more than 270,000 BTC, roughly $16.7 billion, over a two week stretch, with much of that buying concentrated near $59,000. Two sides of the same market moving in opposite directions at the same time.
This is not a new pattern. Analysts have described this specific combination, institutions selling while long term holders accumulate, as a setup that has historically shown up close to prior cycle lows. Separate research comparing the current alignment of falling holder profitability and rising accumulation pointed to two earlier moments as the closest precedents: the March 2020 pandemic crash and the Q4 2022 collapse of FTX. Both, in hindsight, were entry points rather than warnings. None of this guarantees the current period plays out the same way. Bitcoin's market now includes ETFs, corporate treasuries, and sovereign scale capital that did not exist in 2020, which means old patterns deserve scrutiny rather than blind faith. But the behavioral divergence itself, disciplined buyers stepping in exactly when everyone else is stepping out, is worth paying attention to regardless of where price goes next.
The same split shows up beyond on chain wallets. Several institutional trading desks and treasury focused advisers have said publicly that they view current levels as an entry point tied to a multi year adoption thesis, not a call on where price goes next month. That distinction matters. Treating a drawdown as a long horizon opportunity is a different exercise entirely from predicting a bottom, and conflating the two is how disciplined positioning turns into speculation.
Meanwhile, on the other side of the market, a very different story played out. Blockchain analytics firm Nansen tracked roughly 1.48 million wallets that bought into a politically themed memecoin after its early 2025 launch. By the end of June, nearly 989,000 of those wallets, about two in three, were sitting on losses, with combined losses near $3.81 billion. A separate group of roughly 500,000 early buyers captured close to $4 billion in profit before the later wave of retail money arrived. The pattern is familiar to anyone who has watched a hype cycle unfold: the earliest participants extract the gains, and the crowd that arrives after the headlines absorbs the loss. It is not unique to one token. It is closer to the default outcome of chasing a narrative after it has already gone viral.
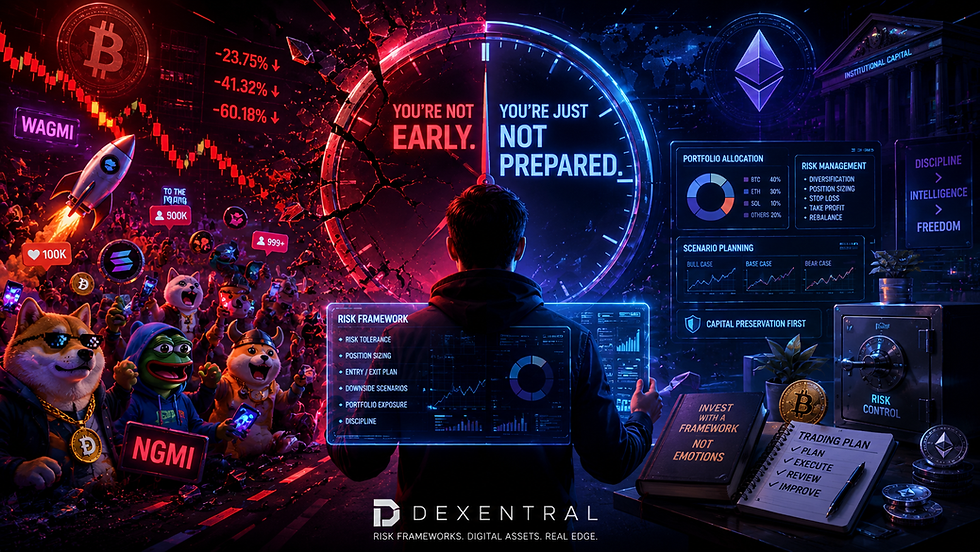
This is the actual divide worth naming, and it has nothing to do with optimism versus pessimism. It has everything to do with process. The buyers accumulating near multi year lows right now are not making a prediction about next week's price. They are following a framework, sizing positions against a thesis, and treating volatility as a variable to manage rather than a signal to panic over. The buyers who chased a memecoin at its peak were doing the opposite: reacting to momentum, entering after the move had already happened, with no plan for what came next.
Extreme fear does put a price on things. The number moves whether anyone is ready for it or not. What separates the two sides of this market is whether someone had a framework in place before that number moved, or whether they are only reacting to it now.
This article is part of DEXENTRAL's Weekly Newsletter Article.


Comments